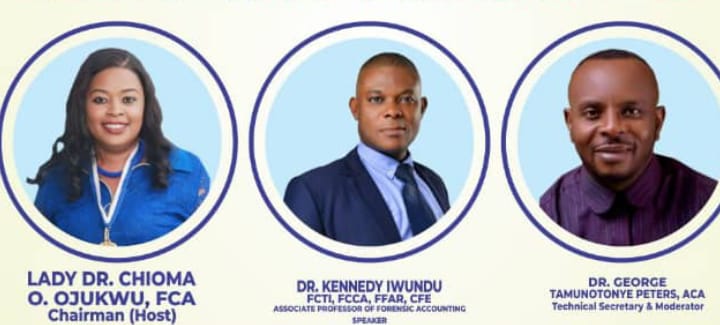

Presented by: DR KENNEDY IWUNDU, FCTI, FCCA, FFAR, CFE
Associate Professor of Forensic Accounting
Preamble
This lecture series is aimed at building capacity of the members of the Institute of Chartered Accountants of Nigeria (ICAN) and the general public. This is the second in the series of the free public lectures and second for the year 2025 powered by ICAN OBIO/AKPOR & District Society.
Participation
The virtual programme had in attendance over 250 participants participants including the Chairman and Host, Lady Lolo Dr Chioma Obianuju Ojukwu, FCA, our Chairman of Session, Prof. Gabriel N. Ogbonna FCA. Also, the Moderators, Associate Professor George Peters, ACA, the District’s Pioneer Technical Secretary, Ably assisted by Dr Mrs. Anita Amieye, ACA: Assistant Chairman, Technical/Training Committee. Our Distinguished Special Guests, Dr Abel Aig Asein, FCA- Executive secretary, Association of Accountancy Bodies in West Africa (ABWA) and Akintoye Solomon, FCA, Head, Port Harcourt III Emerging Tax office, Federal Inland Revenue Service (FIRS) Mr. Chidi Ezema, Chairman CITN South. Some past and present Council Members of ICAN and Chartered Institute of Taxation of Nigeria (CITN); current and past Chairmen and executive members of ICAN and CITN were in attendance. Some Lecturers from the University of Port Harcourt Rivers State University and Ignatius Ajuru University of Education, members of our revered Institute and the general public, and gentlemen of the Press all graced the Webinar session.
Opening
The Chairman of ICAN OBIO/AKPOR & District Society and Host, Dr. Chioma Obianuju Ojukwu, FCA welcomed all participants and specially thanked everyone for joining the second webinar of the District.
The Chairman of the session, Prof. Gabriel N. Ogbonna FCA stated that tax reforms are set to ensure payment of taxes in order to boost the revenue of the nation at large. The Special guests, Dr Abel Aig Asein appreciated the representative of the speaker in person of Mr Akin Tunde for a well delivered paper and threw more light on the presentation, and Akintoye Solomon emphasized that according to the bible old things have passed away and we should imbibe the new tax laws as our bible.
Technical Presentation Proper
The Guest Speaker, Dr Kennedy Iwundu ably represented by Mr. Akin Tunde, noted that The Nigeria Tax Act (from now on referred to as the NTA) is a comprehensive piece of legislation that seeks to outline all taxes in the country hitherto administered by different laws and compress them into a single simplified law. He noted that there is a quadripod or quadruped of taxation which are the tax policy, the legislation, the tax administration and the tax jurisprudence. Tax reform Acts captured the tax legislation, tax administration and tax jurisprudence. The Nigerian tax act captured tax legislation which is aimed at consolidating Nigerian fragmented tax laws into a harmonized statute. The Nigeria tax administration act and the Nigeria Revenue Service (Establishment) act captured the tax administration and practice by establishing a uniform operational framework for tax administration across the federal, state and local governments and collection of tax and non-tax revenue.
Objectives of Nigerian Tax Act
The objective of this Act is to provide a unified fiscal legislation governing taxation in Nigeria. This Act applies throughout Nigeria to any person required to comply with any provision of the tax laws whether personally or on behalf of another person.
Top 18 Key Changes in NTA among which are:
- Company Income Tax (CIT)
Tax Rates Section 56 of NTA states that
• Small company 0 to 50 million turnover is 0%
• Above 50 million turnover is 30%
Small company” means a company that earns gross turnover of N50,000,000 or less per annum with total fixed assets not exceeding N250,000,000, provided that any business providing professional services shall not be classified as a small company. - Taxable profits of non-residents
The NTA expands the scope of the activities of non-resident companies that are subject to tax in Nigeria. Notably, the NTA introduces “force of attraction” rules. Under these rules, certain activities carried out by a non-resident company or its related parties, can be taxed as part of the non-resident company’s permanent establishment (PE) in Nigeria, even if those activities are not physically conducted through the PE. In addition, profits from Engineering, Procurement, and Construction contracts can be taxed in Nigeria, even if some of the activities are performed under separate contracts or outside Nigeria. - Minimum Tax for Non-resident companies
Tax payable by such companies cannot be less than the withholding tax (WHT) rate applicable to the income, or 5% of the income. - Personal Income Tax (PIT)
The NTA eliminates the Consolidated Relief Allowance (CRA) and introduces a rent relief which is 20% of annual rent paid, subject to a maximum of ₦500,000, whichever is lower. The NTA will capture both employment and non- employment income. 31st March as due date for PIT return has been eliminated. PIT return is now annually depending on the accounting date chosen by the individual. - CAPITAL ALLOWANCE
SMEs can now claim full capital allowances without proration, reducing taxable profits and CIT obligations while capital-intensive businesses face delayed tax relief. - VALUE ADDED TAX (VAT)
The VAT vertical distribution formula has been revised as follows:
• Federal Government reduced from 15% to 10%
• State government increased from 50% to 55%
• Local Government remains at 35% - TAX INCENTIVE
A company will be entitled to an additional deduction of 50% in the relevant years of assessment in respect of costs incurred in any 2 calendar years from 2023 to 2025 with respect to the following: wage awards, salary increases, transportation allowance or transport subsidy granted to a low-income worker that bring the gross remuneration of such worker to an amount not exceeding ₦100,000. However, any award or salary increase to any worker earning above ₦100,000 shall not qualify. - ECONOMIC DEVELOPMENT TAX INCENTIVE(EDTI)
The scheme introduces a targeted incentive regime aimed at stimulating capital investment in defined priority sectors. To qualify for this incentive, the Qualifying Capital Expenditure (QCE) to be incurred by the company on or before production day. The NTA also replaces the complex and costly fee structure under the PSI regime with a more equitable model of 0.1% fee on QCE, capped at ₦5million payable each to the NIPC and the Industrial Inspectorate Department (IID). In essence, the maximum fee payable to the NIPC and IID is ₦10million. - TAXATION OF APPROVED ENTITIES IN FREE TRADE ZONES
Where more than 25% of the sales are to the customs territory, tax will be applicable on the profits of the entity in respect of its total sales to the customs territory. However, effective from 1 January 2028, an entity will be fully liable to tax in respect of sales to the customs territory regardless of the percentage of the sales.
Signed:
Dr. (Mrs.) Nengi M. Isagua, FCA
Deputy Bursar
Project Accountant
World Bank Funded Centre
ACE-PUTOR,